Tuesday, October 6, 2026


The Fax-Era Ceiling: How Old-School Management Holds Back German IT
German IT is not short of talent; it is short of decision-makers who understand what they control. Japan shows what happens when a country's resources sit with people who can no longer put them to work. Germany is running the same experiment with something just as valuable: authority over technology.

In Japan, the frozen asset is money. Bloomberg reports that seniors with cognitive decline control about ¥315 trillion, close to half of GDP, and much of it simply sits idle. In Germany, the frozen asset is decision-making. Budgets, hiring and architecture are controlled by a management layer formed in the fax era, and the engineers who could use that authority productively rarely get it.

The comparison is about how institutions allocate control, not about age. Plenty of older leaders are excellent technologists. The problem is a system in which seniority, not competence, decides who steers technical work.

The Japanese lesson: controlled but not used

Japan's "dementia money" problem is a story about capital that is owned but cannot move. In 2018, Bloomberg put assets held by people with dementia at ¥143 trillion, more than a quarter of the economy. Its January 2026 follow-up puts liquid assets controlled by seniors with cognitive decline at about ¥315 trillion ($2 trillion).

The damage comes in three forms:

- Idleness. Banks freeze accounts to protect vulnerable customers, so money leaves circulation in an economy that badly needs spending and investment.

- Mismanagement and fraud. Owners who can no longer judge risk are easy targets, and nobody else is authorised to act for them.

- No succession. Few people hand over control while they are still able to, so the transfer happens too late or not at all.

The core insight is simple: an economy suffers when control and capability separate. The resource exists, but the person holding it cannot use it, and the people who could are locked out.

Germany's version: frozen decision-making

Germany's frozen asset is the authority to decide how technology is built, bought and staffed. Red Robot's August 2026 analysis argues that the country's IT problem is not a talent shortage but a competence-allocation problem: people who understand systems lack authority, and people with authority need not understand systems.

The results show in the rankings. In the Bitkom DESI 2026, compiled by Germany's own tech association, Germany placed 17th of 27 EU countries with 51.1 points, against Denmark's 76.4. It was 13th in 2022 and 14th in 2025. Its score rose slightly while its peers rose faster.

This is where the "fax-era manager" comes in. The term describes a mindset, not a birth year: someone whose model of good management was formed when paper, approval chains and long planning cycles were the safest way to run an organisation. That model works for building machines that must not fail. It breaks down in software, where speed, iteration and reversible mistakes win.

The symptoms: the same three failures

Each failure Japan shows with frozen money has a German twin in frozen management.

FailureJapan: frozen capitalGermany: frozen decisionsIdlenessAccounts locked, money out of circulationAbout 109,000 IT jobs unfilled; roles take nearly 8 months to fill; 61% of firms say candidates' pay demands don't fit their existing salary structureMismanagementOwners can't judge risk, so others exploit themThe Bundeswehr's D-LBO radio programme (about €20 billion) failed field tests; the fix was about €156.7 million for outside consultantsNo successionControl isn't handed over in timeOver 11,000 municipalities buy IT on their own; no shared standards, so the "One for All" reuse principle keeps failing

The consultant reflex deserves a closer look. A manager who cannot judge technical work can still buy a big-name consultancy. That turns personal career risk into a budget line, and it keeps decisions away from the engineers who could have made them.

The same pattern shows in cloud strategy. Red Robot cites surveys in which 82% of German firms want to end dependence on US cloud providers, while 78% remain dependent. Wanting change without delegating the authority to deliver it is exactly what a frozen asset looks like.

Who pays: the business-minded engineer

The biggest loser is the engineer who understands both the technology and the business case. In a healthy system, this person rises to own budgets, products and architecture. In a fax-era system, there is no clear path from building things to deciding things.

The raw material is strong. Germany's dual vocational track fills about 44% of IT roles and is among the best in the world. The engineers who finish an Informatik degree, despite a dropout rate above 50%, are well trained. What happens next is the problem:

- Pay grids cap them. Firms would rather leave a seat empty than pay market rates and disturb existing salary bands.

- Approval chains slow them. Decisions climb several levels because nobody at the bottom is allowed to be wrong.

- Capital starves them. Measured against GDP, the US deploys nearly six times as much venture capital as Germany. In one 2026 quarter, Germany closed a single confirmed deal above €100 million.

The result mirrors Japan's frozen accounts. The capability exists, but it cannot reach the resources it needs. So it leaves for another country, sits in a consultancy, or never starts the company it could have built.

Unfreezing the asset

Japan's answer to frozen money is planned succession: hand over control while the owner can still choose who gets it. Germany needs the same thing for decision rights in technology.

- Put technical authority inside the buyer. No large IT programme without an accountable, technically literate owner on the payroll, not only on a consultancy contract.

- Build a path from engineer to owner. Promote people who ship working systems into budget and product roles, instead of routing every decision upward.

- Pay the market, not the grid. A salary structure that leaves seats empty for eight months is costing more than it saves.

- Standardise interfaces, not purchases. Mandate shared APIs and data formats across the 11,000 municipalities, and let each buy freely behind them.

- Reward reversible mistakes. Judge managers on what they ship, so that shipping something imperfect beats shipping nothing for three years.

None of these steps requires better engineers. All of them require the current decision-makers to hand over some control.

Where the argument has limits

The thesis is strong but not the whole story, and a fair reader should weigh the counterpoints.

- The analogy is a metaphor. Japan's problem involves real cognitive illness; Germany's managers are not impaired. The shared pattern is control separated from capability, nothing more.

- Age is not the variable. Many senior leaders run excellent technical organisations, and many young managers adopt the same risk-averse habits. Incentives and structure matter more than birth year.

- German caution works in places. Deep tech, defence and Mittelstand engineering are doing well. Red Robot notes 2026 rounds such as Stark (€500 million) and Isar Aerospace (€270 million). Where the product is physical and errors are costly, thoroughness pays.

- Structure, not just people. Federalism, data-protection law and a small venture-capital market would slow any management generation. Replacing managers without fixing these would change less than hoped.

The defensible claim is therefore narrower than "old managers are the problem": Germany's software sector is held back by a management culture, rooted in the fax era, that keeps authority away from the people best equipped to use it.

Sources

- Bloomberg, Japan's 'Dementia Money' Is a Warning to the World (January 2, 2026, paywalled)

- Bloomberg, Dementia Sufferers Sit Atop a Mountain of Frozen Assets in Japan (October 16, 2018, paywalled)

- Metropolis Japan, Japan's Captive Capital: Trillions Locked Up In "Dementia Money"

- The Red Robot, Germany's IT Industry Is Not Short of Engineers. It Is Short of Judgement. (August 17, 2026)

- Hans-Werner Sinn, Ifo Viewpoint No. 159: German Gerontocracy (June 2014) https://redrobot.online/2026/10/06/the-fax-era-ceiling-how-old-school-management-holds-back-german-it/

AI Agents Get Their Own Money Rails: The ECB and Stripe Build for Machine Shoppers

AI Agents Get Their Own Money Rails: The ECB and Stripe Build for Machine Shoppers

AI agents are getting their own money rails. In the same week, the European Central Bank opened a call for firms to explore AI-agent and machine-to-machine payments on the digital euro, and Stripe said agentic purchases through its Link wallet grew 38x in a month, adding tools so agents can handle changing prices, analyse spending and offer purchase protection. One is a central bank drafting rules for 2027; the other is a payments company already processing agent purchases today. Together they show that agent commerce is moving from experiment to infrastructure — and that the checkout, not the storefront, is where it will be won.


Go deeper: an agent can only pay you if your checkout can settle its purchase. Our series walks through it — Building Agentic Commerce, Part 4: settling the transaction.


The central bank: agents on the drawing board


The ECB opened applications on Monday for a new round of its digital euro innovation platform, Cointelegraph reported. An experimentation track from January to June 2027 will have participants prototype e-receipts, multiparty transactions, conditional payments and new front-end features. Workshops in the first half of 2027 will cover AI-enabled payments, micropayments, machine-to-machine interactions and public-service uses. The ECB has separately selected 36 banks and payment firms, including Revolut, Stripe and Deutsche Bank, for a 12-month pilot starting in the second half of 2027. Any issuance still requires EU legislation and a further ECB decision.


The payment network: agents already buying


Stripe says popular personal agents — including Meta's new Muse, Grok Bot and Instinct — now use Link's wallet for agents, and that agentic purchases through Link grew 38x over the past month. It announced three upgrades:


- Incremental authorisation. When the final price exceeds the approved amount — a checked bag added to a flight — the agent can raise the approval instead of restarting the purchase. When it hits obstacles, Link provides guidance, such as a URL for the consumer to complete a 3D Secure challenge.
- Financial insights. With permission, agents can analyse a consumer's purchase history, via Stripe's Financial Connections, to suggest stores and budgets. Stripe says it covers more than 12,000 financial institutions and over 97% of US bank accounts; consumers can revoke access at any time.
- Purchase protection. Eligible agent purchases can be covered for accidental damage, lost items, price drops and returns. Muse is the first agent to offer it.

Next, Stripe plans spending controls so consumers can give an agent a budget for a task without approving each transaction.


The read


Look at what both are building: not new ways to browse, but new ways to settle. Conditional and multiparty payments, e-receipts, incremental authorisation, budgets, protection when the agent makes a mistake — every item is about the moment money moves and what happens when it goes wrong. That is where agent commerce is hard, because an agent doesn't see a price once and click "buy"; it negotiates changing totals, taxes, add-ons and approvals.


For merchants and platform builders, the implication is that the checkout has to become machine-legible: authoritative server-side prices, invoices that can change line by line, clear approval limits and settlement records that both the customer and the agent can trust. The rails are arriving from both the public and private side. The businesses ready to accept agent payments will be those whose invoice logic was built to be called, not just clicked.


Written for Red Robot with AI assistance and human editing. Based on reporting by Cointelegraph and Stripe.

https://redrobot.online/2026/09/30/ai-agents-get-their-own-money-rails-the-ecb-and-stripe-build-for-machine-shoppers/

Tuesday, September 22, 2026

A Self-Hosted Office Suite With No 'eval': How VBWD Office Is Built

A Self-Hosted Office Suite With No 'eval': How VBWD Office Is Built
An engineering review of VBWD Office from its public repos: one storage spine and three products (Space, Docs, Spreadsheets), encrypted at rest, capability-based sharing, and a spreadsheet engine that parses formulas to an AST instead of running eval.

A self-hosted file vault, editor and spreadsheet you can actually audit — and the design choices are more interesting than the features.

"You can't self-host a real office suite — that's why everyone rents Google Docs." A new engineering review of VBWD Office, built from its three public repositories, is a working argument against that: a self-hosted file vault, rich-text editor and spreadsheet that run on infrastructure you control. The design decisions are more interesting than the feature list.


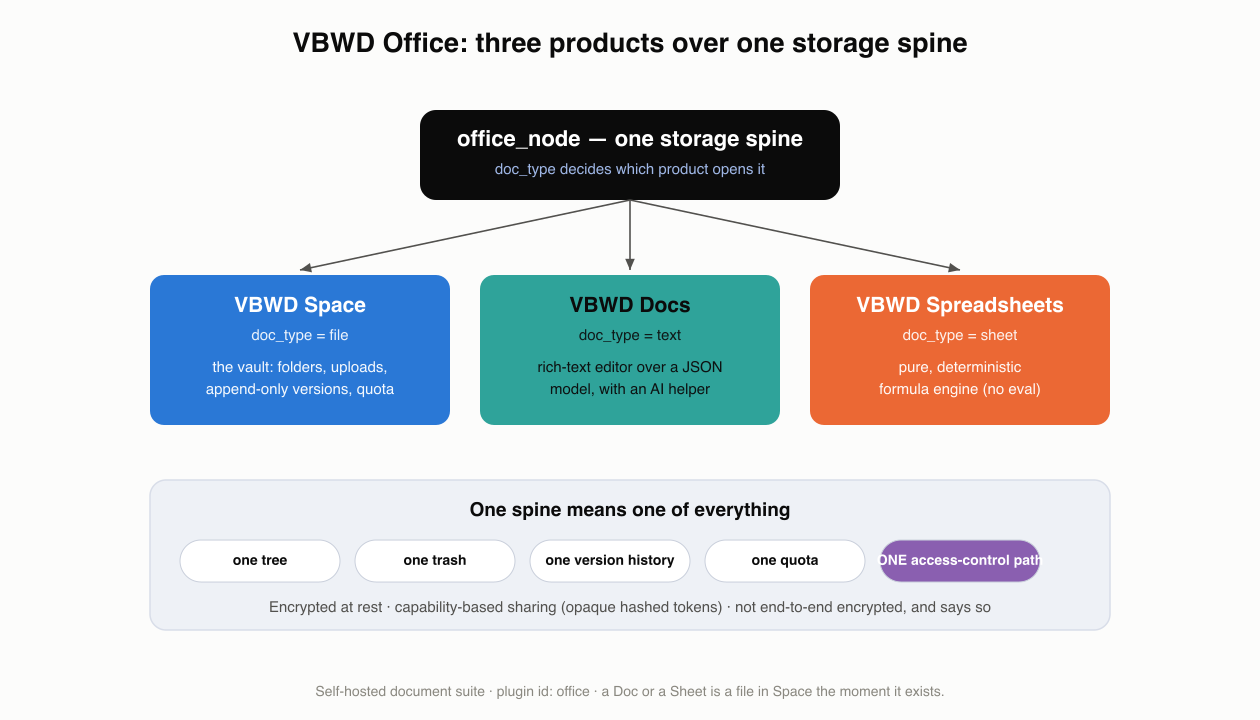
Diagram: VBWD Office — one office_node storage spine branching into Space, Docs and Spreadsheets with one shared access-control path.

One spine, three products


The suite refuses to build three apps. As the review on VBWD explains:


A document is a single record — an office_node — and its doc_type decides which product opens it

— file is the Space vault, text is the Docs editor, sheet is the spreadsheet. They share one tree, one trash, one version history, one quota and one access-control path, so every "can this person touch this?" question is answered in one place instead of three.


Honest security, and no eval


What stands out is the candour. Documents are encrypted at rest but the suite is explicitly not end-to-end encrypted, because AI, preview and search need to read them — and the review says so plainly:


anyone claiming E2EE while holding the keys would be misleading you

The detail engineers will appreciate is the spreadsheet engine. As the review notes:


A spreadsheet is, functionally, user-supplied code running on your server

— so the naive approach, a language eval, would be remote code execution with extra steps. VBWD Office instead lexes formulas, parses them to an AST and runs them in an interpreter, with a purity test enforcing the boundary in CI. Sharing is a capability (an opaque hashed token with a permission and expiry), not a session, and invalid tokens return a 404 indistinguishable from one that never existed.


The full review is published on VBWD; the code is public across vbwd-plugin-office and its admin and user front-end repos.


Written for Red Robot with AI assistance and human editing. Adapted from an original analysis published on VBWD.

https://redrobot.online/2026/09/09/a-self-hosted-office-suite-with-no-eval-how-vbwd-office-is-built/

Thursday, August 20, 2026

Germany's IT Industry Is Not Short of Engineers. It Is Short of Judgement.

Germany's IT Industry Is Not Short of Engineers. It Is Short of Judgement.

Europe's largest economy places 17th out of 27 in its own industry association's digital ranking. Not 17th in some hostile foreign index — 17th in the Bitkom DESI 2026, compiled by Germany's own tech lobby, using the European Commission's methodology, presumably with every incentive to be generous. Germany scored 51.1 points. Denmark, a country with roughly the population of Hesse, scored 76.4.


And Germany is falling, not rising. It ranked 13th in 2022, 14th in 2025, 17th now. The score went up slightly. Everyone else went up faster.


This is the part that should end the comfortable conversation about "challenges" and "transformation journeys." Germany is not behind because it started late. Germany is behind because it is being outpaced, in real time, by countries it likes to think of as small.


The comfortable lie about the talent shortage


The standard German explanation is a labour shortage. Bitkom reports roughly 109,000 unfilled IT positions. Eighty-five percent of surveyed companies complain about a shortage of IT professionals; 79 percent expect it to get worse. It takes, on average, nearly eight months to fill an open IT role.


Look closer at those numbers and a different story falls out.


Around one in four German companies receives essentially no applications at all for advertised IT roles. Not "too few qualified candidates" — no candidates. That is not a talent shortage. That is a company nobody wants to work for, advertising a job nobody wants, at a salary nobody accepts, in a city nobody moves to, through an HR process that takes eight months to say yes.


Meanwhile 61 percent of firms cite candidate salary expectations that don't fit their "grown salary structure" — a magnificent piece of German corporate poetry meaning: we would rather leave the seat empty for eight months than pay market rate and disturb the pay grid of people who have been here since 2009.


The universities do leak badly. Over 81,000 people began computer science degrees in 2024; around 39,000 graduated. The dropout rate has sat above 50 percent for years. That is a real and damning number, and Bitkom is right to say the shortage cannot be closed from the universities.


But "over half drop out" is not evidence that German engineers are badly educated. It is evidence of a filter set to industrial-grinder mode by institutions that measure their own quality by how many people they fail. The ones who come out the other end of a German Informatik degree or a Fachinformatiker apprenticeship are, on average, extremely solid. Forty-four percent of IT roles in Germany get filled by dual-education graduates, and that vocational track is genuinely one of the best in the world.


The problem is not the raw material. It is what happens to it afterwards.


The consultant-industrial complex


Consider D-LBO — the Bundeswehr's "Digitalisation of Land-Based Operations," a programme in the range of €20 billion whose purpose is to let German soldiers talk to each other by radio.


As of late 2025 and early 2026 it did not work. Field tests were aborted. Voice radio between retrofitted Leopard 2 A7V tanks was assessed as inadequate, with transmissions degraded to noise. Soldiers could not reliably tell whether a message had been sent. Friendly Force Tracking barely functioned, which in a real engagement is not an inconvenience but a friendly-fire risk. Tanks could hold a single fixed frequency and could not run security and tactical networks simultaneously.


The response was not to fire the people responsible for the architecture. The response, per reporting on internal Ministry of Defence papers, was to procure roughly €156.7 million in external support through the Bundeswehr's own IT company, routed to Capgemini, PwC and MSG Systems — at daily rates discussed in the budget committee of €1,200 and up per consultant.


This is the central pathology of German enterprise and public IT, and it has nothing to do with engineers. A programme fails on requirements, integration and accountability — three management functions — and the corrective action is to buy more management. The consultancies are not the villains here; they are simply answering a demand signal. The demand signal is a class of decision-makers who cannot evaluate technical work, cannot be held responsible for technical outcomes, and have discovered that hiring PwC converts personal career risk into a line item.


You can watch the same reflex in miniature at any mid-sized German company: the Digitalisierungsstrategie that produces a 90-slide deck and no shipped software; the Lenkungskreis that meets fortnightly for two years; the architecture decision escalated four levels because nobody at level one is allowed to be wrong.


Eleven thousand kingdoms


The EU Commission's 2026 Digital Decade report on Germany names the structural cause with unusual bluntness. Germany's "One for All" principle — build a digital service once in one state, reuse it everywhere — keeps failing for lack of overarching standards and an extremely fragmented IT landscape spread across more than 11,000 municipalities.


Eleven thousand. Each with procurement autonomy. Each with a Kämmerer who has opinions. Each capable of buying its own citizen portal from its own regional supplier.


Digital services for citizens actually declined by about a percent, to 78.11 out of 100, against an EU average of 84.64. Fibre-to-the-premises coverage rose to about 44 percent while the EU average hit 74 percent — second-to-last in Europe. And where the fibre does exist, roughly a quarter of available connections are actually used, because German households look at a working VDSL line and see no reason to change.


That last statistic is the whole country in one number. The infrastructure gets built. Nobody adopts it. Then everyone complains that Germany has bad infrastructure.


Federalism is a legitimate constitutional value. It is also, in software, a catastrophic architecture: 11,000 independent buyers with no shared interface contract is not subsidiarity, it is a distributed system with no protocol. Any competent engineer would recognise it instantly as the problem. The point is that no competent engineer is in the room where that decision gets made.


Capital that punishes ambition


German startups raised somewhere between €7.2 billion (KfW) and €8.4 billion (EY) in 2025, depending on methodology. In relative terms the picture is uglier: measured against GDP, the United States deploys nearly six times as much venture capital as Germany, the UK nearly four times, and France more than 50 percent more.


The deal-level gap is starker still. In a single quarter of 2026, four American AI companies raised a combined figure in the region of $188 billion. The UK closed multiple late-stage AI rounds above a billion dollars. France produced a $1 billion seed round. Germany, in that entire quarter, produced one confirmed deal above €100 million.


Europe's largest tech company remains SAP — sometimes called Der Eine, "The One," which is funny until you notice it is a demographic observation about an entire continent. SAP is an excellent company. It is also forty-plus years old, and the fact that Germany's tech identity still rests on it says more about the four decades since than about SAP.


Sovereignty as performance


The most revealing single data point in German IT in 2026: 82 percent of German companies say they want to end technical dependence on US cloud providers. 78 percent remain dependent in practice.


Three American providers hold around 70 percent of the European cloud infrastructure market; European providers hold about 15. Over 90 percent of German companies use cloud services, and roughly two-thirds say they could not operate without the hyperscalers.


Germany has responded with GAIA-X, the Sovereign Cloud Stack, a Deutschland-Stack contract of around €250 million awarded in May 2026 to T-Systems/SAP and an SVA/Schwarz Digits/Codesphere consortium, and Schwarz Group's €11 billion STACKIT commitment. Some of this is real and some of it will matter. But AWS opened its European Sovereign Cloud in Brandenburg in January 2026, and the honest reading of the market is that the sovereignty debate has so far been a very effective way to sell more American cloud with a German flag on the invoice.


Wanting something at 82 percent and doing it at 22 percent is not a strategy. It is a national mood.


What is actually working


A critique that cannot name the exceptions is just a grudge, so: the exceptions are real and they are informative.


Germany's genuine strengths in 2026 are hardware-adjacent and science-heavy. Deep tech and defence are pacing German VC toward its best year since 2021 — Stark's €500 million, Isar Aerospace's €270 million, Black Forest Labs' $300 million, Tubulis' $360 million. TUM and the Munich research-spinout pipeline work. The dual vocational system works. Mittelstand engineering discipline is a real asset and always was.


Note the pattern: Germany performs where the artefact is physical, the requirements are stable, the tolerance for error is low, and the timeline is measured in years. Germany underperforms where the artefact is software, requirements change monthly, error tolerance is high, and the timeline is measured in weeks. This is not a skills gap. It is a temperament and governance mismatch — a country optimised for Gründlichkeit trying to compete in a discipline that rewards reversible mistakes.


What would actually change it


None of the following requires better engineers.


- Make the buyer competent. Public IT procurement should require technical authority inside the procuring body. If a €20 billion radio programme has no accountable chief architect on the government payroll, the outcome is already determined.
- Impose interface contracts, not shared software. Stop trying to make 11,000 municipalities buy the same product. Mandate the API, the data schema, the eID integration. Let them buy whatever they want behind it.
- Fix the eight months. A hiring process that takes eight months is a self-inflicted wound. So is a pay grid that forbids paying market rate.
- Stop treating a 50 percent dropout rate as a quality signal. It is a manufacturing defect rate, and no German factory would tolerate it.
- Reward reversible failure. The single largest cultural blocker is that in most German organisations, a manager who ships something imperfect is punished more than a manager who ships nothing for three years. Until that inverts, everything else is decoration.

Germany does not have a technology problem. It has a competence-allocation problem: the people who understand the systems have no authority, and the people with authority have no obligation to understand the systems. That is a solvable problem. It is also, on current evidence, one Germany is not solving fast enough to stay ahead of Denmark.


Sources


- Bitkom DESI Index 2026 — https://www.bitkom.org/EN/Bitkom-DESI-2026
- heise online, "Germany (not) digital: Administration still loading" — https://www.heise.de/en/news/Germany-not-digital-Administration-still-loading-11398504.html
- heise online, "EU Digital Decade Report 2026: Germany's progress is slow" — https://www.heise.de/en/news/EU-Digital-Decade-Report-2026-Germany-s-progress-is-slow-11335819.html
- Bitkom, "Der Arbeitsmarkt für IT-Fachkräfte" (Studienbericht 2026) — https://www.bitkom.org/Bitkom/Publikationen/Der-Arbeitsmarkt-fuer-IT-Fachkraefte
- Bitkom press release, IT-Fachkräfte figures — https://www.bitkom.org/Presse/Presseinformation/Deutschland-fehlen-IT-Fachkraefte
- heise online, "Bundeswehr's Digital Radio Disaster: Millions for Consultants to Fix It" — https://www.heise.de/en/news/Bundeswehr-s-Digital-Radio-Disaster-Millions-for-Consultants-to-Fix-It-11067142.html
- PitchBook, "Germany's deep tech edge drives acceleration in VC funding" — https://pitchbook.com/news/articles/germanys-deep-tech-edge-drives-acceleration-in-vc-funding
- Startuprad.io, "Germany's VC Market After the Correction" (KfW / EY figures) — https://www.startuprad.io/post/germany-vc-market-after-correction-stable-not-strong
- Fortune, on SAP as Europe's sole scaled tech company — https://fortune.com/2025/09/08/does-sap-prove-the-rule-that-europe-cant-scale-tech-companies-innovation
- Digital Chiefs, "Digital Sovereignty 2026" — https://www.digital-chiefs.de/en/digital-sovereignty-2026-gaia-x-delos-cloud-and-europes-response-to-the-cloud-ac/
- Broadcom, "Three Predictions for Sovereign Cloud in 2026" — https://news.broadcom.com/sovereign-cloud/three-predictions-for-sovereign-cloud-in-2026
- Cloudmagazin, on the Deutschland-Stack award — https://www.cloudmagazin.com/en/2026/05/21/germany-stack-federal-ki-cloud-sovereign/ https://redrobot.online/2026/08/17/germanys-it-industry-is-not-short-of-engineers-it-is-short-of-judgement/

Monday, August 17, 2026


Germany's IT Industry Is Not Short of Engineers. It Is Short of Judgement.
Europe's largest economy places 17th out of 27 in its own industry association's digital ranking. Not 17th in some hostile foreign index — 17th in the Bitkom DESI 2026, compiled by Germany's own tech lobby, using the European Commission's methodology, presumably with every incentive to be generous. Germany scored 51.1 points. Denmark, a country with roughly the population of Hesse, scored 76.4.

And Germany is falling, not rising. It ranked 13th in 2022, 14th in 2025, 17th now. The score went up slightly. Everyone else went up faster.

This is the part that should end the comfortable conversation about "challenges" and "transformation journeys." Germany is not behind because it started late. Germany is behind because it is being outpaced, in real time, by countries it likes to think of as small.

The comfortable lie about the talent shortage

The standard German explanation is a labour shortage. Bitkom reports roughly 109,000 unfilled IT positions. Eighty-five percent of surveyed companies complain about a shortage of IT professionals; 79 percent expect it to get worse. It takes, on average, nearly eight months to fill an open IT role.

Look closer at those numbers and a different story falls out.

Around one in four German companies receives essentially no applications at all for advertised IT roles. Not "too few qualified candidates" — no candidates. That is not a talent shortage. That is a company nobody wants to work for, advertising a job nobody wants, at a salary nobody accepts, in a city nobody moves to, through an HR process that takes eight months to say yes.

Meanwhile 61 percent of firms cite candidate salary expectations that don't fit their "grown salary structure" — a magnificent piece of German corporate poetry meaning: we would rather leave the seat empty for eight months than pay market rate and disturb the pay grid of people who have been here since 2009.

The universities do leak badly. Over 81,000 people began computer science degrees in 2024; around 39,000 graduated. The dropout rate has sat above 50 percent for years. That is a real and damning number, and Bitkom is right to say the shortage cannot be closed from the universities.

But "over half drop out" is not evidence that German engineers are badly educated. It is evidence of a filter set to industrial-grinder mode by institutions that measure their own quality by how many people they fail. The ones who come out the other end of a German Informatik degree or a Fachinformatiker apprenticeship are, on average, extremely solid. Forty-four percent of IT roles in Germany get filled by dual-education graduates, and that vocational track is genuinely one of the best in the world.

The problem is not the raw material. It is what happens to it afterwards.

The consultant-industrial complex

Consider D-LBO — the Bundeswehr's "Digitalisation of Land-Based Operations," a programme in the range of €20 billion whose purpose is to let German soldiers talk to each other by radio.

As of late 2025 and early 2026 it did not work. Field tests were aborted. Voice radio between retrofitted Leopard 2 A7V tanks was assessed as inadequate, with transmissions degraded to noise. Soldiers could not reliably tell whether a message had been sent. Friendly Force Tracking barely functioned, which in a real engagement is not an inconvenience but a friendly-fire risk. Tanks could hold a single fixed frequency and could not run security and tactical networks simultaneously.

The response was not to fire the people responsible for the architecture. The response, per reporting on internal Ministry of Defence papers, was to procure roughly €156.7 million in external support through the Bundeswehr's own IT company, routed to Capgemini, PwC and MSG Systems — at daily rates discussed in the budget committee of €1,200 and up per consultant.

This is the central pathology of German enterprise and public IT, and it has nothing to do with engineers. A programme fails on requirements, integration and accountability — three management functions — and the corrective action is to buy more management. The consultancies are not the villains here; they are simply answering a demand signal. The demand signal is a class of decision-makers who cannot evaluate technical work, cannot be held responsible for technical outcomes, and have discovered that hiring PwC converts personal career risk into a line item.

You can watch the same reflex in miniature at any mid-sized German company: the Digitalisierungsstrategie that produces a 90-slide deck and no shipped software; the Lenkungskreis that meets fortnightly for two years; the architecture decision escalated four levels because nobody at level one is allowed to be wrong.

Eleven thousand kingdoms

The EU Commission's 2026 Digital Decade report on Germany names the structural cause with unusual bluntness. Germany's "One for All" principle — build a digital service once in one state, reuse it everywhere — keeps failing for lack of overarching standards and an extremely fragmented IT landscape spread across more than 11,000 municipalities.

Eleven thousand. Each with procurement autonomy. Each with a Kämmerer who has opinions. Each capable of buying its own citizen portal from its own regional supplier.

Digital services for citizens actually declined by about a percent, to 78.11 out of 100 scores, against an EU average of 84.64. Fibre-to-the-premises coverage rose to about 44 percent while the EU average hit 74 percent — second-to-last in Europe. And where the fibre does exist, roughly a quarter of available connections are actually used, because German households look at a working VDSL line and see no reason to change.

That last statistic is the whole country in one number. The infrastructure gets built. Nobody adopts it. Then everyone complains that Germany has bad infrastructure.

Federalism is a legitimate constitutional value. It is also, in software, a catastrophic architecture: 11,000 independent buyers with no shared interface contract is not subsidiarity, it is a distributed system with no protocol. Any competent engineer would recognise it instantly as the problem. The point is that no competent engineer is in the room where that decision gets made.

Capital that punishes ambition

German startups raised somewhere between €7.2 billion (KfW) and €8.4 billion (EY) in 2025, depending on methodology. In relative terms the picture is uglier: measured against GDP, the United States deploys nearly six times as much venture capital as Germany, the UK nearly four times, and France more than 50 percent more.

The deal-level gap is starker still. In a single quarter of 2026, four American AI companies raised a combined figure in the region of $188 billion. The UK closed multiple late-stage AI rounds above a billion dollars. France produced a $1 billion seed round. Germany, in that entire quarter, produced one confirmed deal above €100 million.

Europe's largest tech company remains SAP — sometimes called Der Eine, "The One," which is funny until you notice it is a demographic observation about an entire continent. SAP is an excellent company. It is also forty-plus years old, and the fact that Germany's tech identity still rests on it says more about the four decades since than about SAP.

Sovereignty as performance

The most revealing single data point in German IT in 2026: 82 percent of German companies say they want to end technical dependence on US cloud providers. 78 percent remain dependent in practice.

Three American providers hold around 70 percent of the European cloud infrastructure market; European providers hold about 15. Over 90 percent of German companies use cloud services, and roughly two-thirds say they could not operate without the hyperscalers.

Germany has responded with GAIA-X, the Sovereign Cloud Stack, a Deutschland-Stack contract of around €250 million awarded in May 2026 to T-Systems/SAP and an SVA/Schwarz Digits/Codesphere consortium, and Schwarz Group's €11 billion STACKIT commitment. Some of this is real and some of it will matter. But AWS opened its European Sovereign Cloud in Brandenburg in January 2026, and the honest reading of the market is that the sovereignty debate has so far been a very effective way to sell more American cloud with a German flag on the invoice.

Wanting something at 82 percent and doing it at 22 percent is not a strategy. It is a national mood.

What is actually working

A critique that cannot name the exceptions is just a grudge, so: the exceptions are real and they are informative.

Germany's genuine strengths in 2026 are hardware-adjacent and science-heavy. Deep tech and defence are pacing German VC toward its best year since 2021 — Stark's €500 million, Isar Aerospace's €270 million, Black Forest Labs' $300 million, Tubulis' $360 million. TUM and the Munich research-spinout pipeline work. The dual vocational system works. Mittelstand engineering discipline is a real asset and always was.

Note the pattern: Germany performs where the artefact is physical, the requirements are stable, the tolerance for error is low, and the timeline is measured in years. Germany underperforms where the artefact is software, requirements change monthly, error tolerance is high, and the timeline is measured in weeks. This is not a skills gap. It is a temperament and governance mismatch — a country optimised for Gründlichkeit trying to compete in a discipline that rewards reversible mistakes.

What would actually change it

None of the following requires better engineers.

- Make the buyer competent. Public IT procurement should require technical authority inside the procuring body. If a €20 billion radio programme has no accountable chief architect on the government payroll, the outcome is already determined.

- Impose interface contracts, not shared software. Stop trying to make 11,000 municipalities buy the same product. Mandate the API, the data schema, the eID integration. Let them buy whatever they want behind it.

- Fix the eight months. A hiring process that takes eight months is a self-inflicted wound. So is a pay grid that forbids paying market rate.

- Stop treating a 50 percent dropout rate as a quality signal. It is a manufacturing defect rate, and no German factory would tolerate it.

- Reward reversible failure. The single largest cultural blocker is that in most German organisations, a manager who ships something imperfect is punished more than a manager who ships nothing for three years. Until that inverts, everything else is decoration.

Germany does not have a technology problem. It has a competence-allocation problem: the people who understand the systems have no authority, and the people with authority have no obligation to understand the systems. That is a solvable problem. It is also, on current evidence, one Germany is not solving fast enough to stay ahead of Denmark.

Sources

- Bitkom DESI Index 2026 — https://www.bitkom.org/EN/Bitkom-DESI-2026

- heise online, "Germany (not) digital: Administration still loading" — https://www.heise.de/en/news/Germany-not-digital-Administration-still-loading-11398504.html

- heise online, "EU Digital Decade Report 2026: Germany's progress is slow" — https://www.heise.de/en/news/EU-Digital-Decade-Report-2026-Germany-s-progress-is-slow-11335819.html

- Bitkom, "Der Arbeitsmarkt für IT-Fachkräfte" (Studienbericht 2026) — https://www.bitkom.org/Bitkom/Publikationen/Der-Arbeitsmarkt-fuer-IT-Fachkraefte

- Bitkom press release, IT-Fachkräfte figures — https://www.bitkom.org/Presse/Presseinformation/Deutschland-fehlen-IT-Fachkraefte

- heise online, "Bundeswehr's Digital Radio Disaster: Millions for Consultants to Fix It" — https://www.heise.de/en/news/Bundeswehr-s-Digital-Radio-Disaster-Millions-for-Consultants-to-Fix-It-11067142.html

- PitchBook, "Germany's deep tech edge drives acceleration in VC funding" — https://pitchbook.com/news/articles/germanys-deep-tech-edge-drives-acceleration-in-vc-funding

- Startuprad.io, "Germany's VC Market After the Correction" (KfW / EY figures) — https://www.startuprad.io/post/germany-vc-market-after-correction-stable-not-strong

- Fortune, on SAP as Europe's sole scaled tech company — https://fortune.com/2025/09/08/does-sap-prove-the-rule-that-europe-cant-scale-tech-companies-innovation

- Digital Chiefs, "Digital Sovereignty 2026" — https://www.digital-chiefs.de/en/digital-sovereignty-2026-gaia-x-delos-cloud-and-europes-response-to-the-cloud-ac/

- Broadcom, "Three Predictions for Sovereign Cloud in 2026" — https://news.broadcom.com/sovereign-cloud/three-predictions-for-sovereign-cloud-in-2026

- Cloudmagazin, on the Deutschland-Stack award — https://www.cloudmagazin.com/en/2026/05/21/germany-stack-federal-ki-cloud-sovereign/ https://redrobot.online/2026/08/17/germanys-it-industry-is-not-short-of-engineers-it-is-short-of-judgement/

Monday, August 10, 2026

The Paid Micro-Audit: How Freelancers Can Turn a 30-Minute Opinion Into an Owned Product

The Paid Micro-Audit: How Freelancers Can Turn a 30-Minute Opinion Into an Owned Product
The 15-to-30-minute expert audit — 'review my Dockerfile', 'tear down my landing page', 'audit my checkout for security holes' — is one of the highest-margin things a specialist can sell, and one of the worst-monetised. A practical guide to productising async micro-audits on infrastructure you own: fixed-scope offers, pay-to-book, event-driven async delivery, and a client list that's yours instead of a marketplace's. Plus the four-week go-to-market.

There's a product hiding inside almost every experienced freelancer's inbox, and most never sell it properly: the fifteen-to-thirty-minute expert opinion. People pay real money for a fast, expert answer — but the tooling around it is a mess of DMs, ad-hoc payment links, and calendars that don't talk to invoices.

There's a product hiding inside almost every experienced freelancer's inbox, and most never sell it properly. It's the fifteen-to-thirty-minute expert opinion — "review my Dockerfile," "tear down my landing page," "is my AWS bill insane?", "audit my checkout flow for security holes." People want these constantly, they're willing to pay real money for a fast, expert answer, and the person delivering them already has the expertise. The micro-audit is one of the highest-margin products a specialist can sell. It's also one of the worst-monetised, because the tooling around it is a mess of DMs, ad-hoc PayPal links, and calendars that don't talk to invoices.


This is a walkthrough of how to turn that scattered demand into a real, productised micro-audit business — the kind you can stand up in a couple of days and start selling this month — and, specifically, how to build the machinery so you own it instead of renting it from a marketplace that takes a cut and keeps your clients.


Why the async micro-audit is such a good product


Three properties make it unusually attractive. First, it's fixed-scope: "a 30-minute security review of one repository" has clear boundaries, so it doesn't sprawl into unpaid consulting the way open-ended work does. Second, done right it's asynchronous: the client submits their artifact, you review it on your own schedule and send back a written teardown — no calendar Tetris, no timezone pain, and you can batch the work. Third, the perceived value is high relative to your time: a tight, expert audit that saves someone a costly mistake is easily worth $99–$299, and it takes you far less than an hour once you've done a few.


Stack those together and you have something that behaves like a product even though it's expertise: repeatable, packageable, and scalable up to the limit of your attention. The only thing standing between most freelancers and this business is the plumbing — taking payment up front, capturing the artifact, tracking the queue, and delivering the result — which is exactly the part that shouldn't require building a SaaS from scratch.


The monetisation trap most freelancers fall into


There are two common ways people sell audits today, and both leak value. The first is the freelance marketplace: convenient reach, but it takes a meaningful cut of every job and, more importantly, owns the client relationship — the repeat business and the referrals accrue to the platform, not to you. The second is fully manual: a DM, a PayPal link, a Google Doc, and a lot of chasing. It keeps 100% of the money but costs you in friction, no-shows, unpaid invoices, and an experience that doesn't feel like a product. What you actually want is the middle path that almost nobody sets up: your own booking-and-payment system, where the client pays up front, the intake is structured, and the whole relationship is yours.


How to build it on an owned stack


This is where a platform that already ships the components collapses the build to a couple of days. On the self-hosted, source-available VBWD stack, the pieces you need are switch-on capabilities rather than things to engineer:


- Productise the offer. Define each audit as a fixed-scope, fixed-price item — "$129 · 30-minute code & security audit of one service" — rather than an hourly rate. Clarity is what makes it sell.
- Booking + accounts. Use the booking capability for the two modes that matter: rapid slots for anyone who wants a live 30 minutes, and async intake for the submit-and-queue flow (a form that captures the repo link, the landing-page URL, the context). User accounts give repeat clients a home and a history.
- Payment up front. Wire payments so booking is paying — the slot or the async job isn't confirmed until it's paid. That single decision eliminates no-shows and invoice-chasing. Offer credit or token packs too, so a client can buy "five audits" at a discount and draw them down.
- Async delivery, automated around you. Because the core is event-driven, a paid booking is a domain event. A native webhook can ping you (in Telegram or email) the moment a job is paid and ready to work, and ping the client the moment you mark the written audit delivered. The deliverable itself — the teardown — can live as gated content the client accesses in their account. You do the expert part; the system does the choreography.
- Own the relationship. Because it's self-hosted, the client list, the payment history and the repeat business are yours — not a marketplace's. The moment a client comes back for a second audit, that decision pays off. (Booking data is also sensitive customer data, which is its own reason to keep it in your perimeter.)

Packaging and pricing that actually converts


Keep the first offer brutally specific. Not "consulting" — one named audit, one price, one turnaround ("48-hour written security review of a single service, $129"). Once that sells, ladder it: a single audit, a discounted five-pack for teams who'll need them repeatedly, and — the real prize — a monthly retainer where you audit their pull requests or landing pages on an ongoing basis. The single audit is the front door; the retainer is the business. Fixed scope and paid-up-front keep every rung of that ladder clean.


The four-week go-to-market


The build is the easy part; here's the selling. Spend day one or two standing up one productised audit with booking and payment. Then write a genuinely good one-page offer for that single audit — who it's for, exactly what they get, the turnaround, the price — and take it directly to where your buyers already are: Indie Hackers, r/SideProject and r/microSaaS, the relevant Slack and Discord communities, and your own network. Lead with proof: offer the first few audits at a discount (or free, for a testimonial), do them exceptionally well, and turn the results into the social proof that sells the next ten. Closing three to five clients in the first week is a realistic target for a specific, well-scoped offer — and each happy client is both revenue and a referral.


The honest caveats


Two, because they matter. First, this is a productised service, not passive SaaS: your expertise and attention are the constraint, and async delivery eases the scheduling pain but doesn't remove the fact that you still have to do the audit. Scaling past your own hours means raising prices, packaging into retainers, or eventually bringing in other reviewers — not just more traffic. Second, the platform makes the machinery fast to build; it does nothing for the distribution, which is still the hard part and still yours. What you gain is the ability to spend your four weeks finding clients instead of building a checkout.


This is one of ten such buildable product ideas we sketched in the micro-SaaS roundup; the micro-audit is the one with the shortest path from "I have a skill" to "I have paying clients." If you want to see the booking-and-payment side stood up against your specific audit offer, request a free assessment and bring the one audit you'd sell first.


VBWD is source-available — get the SDK on GitHub.

https://vbwd.cc/blog/2026/vbwd/agency-playbook-owned-products-on-vbwd

Friday, August 7, 2026

Training AI Is Ruinously Expensive. MIT Taught Models to Shrink Themselves While They Learn.

Training AI Is Ruinously Expensive. MIT Taught Models to Shrink Themselves While They Learn.

Training a large AI model is expensive in every currency that matters — dollars, time, energy, and scarce compute. The usual ways to end up with a small, fast model both waste some of that: either train a giant one and trim it down afterward, or train a small one from scratch and accept weaker results. Researchers at MIT's Computer Science and Artificial Intelligence Laboratory (CSAIL) and collaborators say they've found a third path that sidesteps the trade-off — compressing a model during training instead of after. The work was reported by MIT News.


The technique, called CompreSSM, targets a family of architectures known as state-space models, which underpin language processing, audio generation, and robotics. Borrowing mathematical tools from control theory, it identifies which parts of a model are pulling their weight and which are dead weight, then surgically removes the useless components early in training. "It's essentially a technique to make models grow smaller and faster as they are training," said lead author Makram Chahine, a PhD student in electrical engineering and computer science and a CSAIL affiliate. "During learning, they're also getting rid of parts that are not useful to their development."


The key insight is that the relative importance of a model's internal components settles surprisingly early. Using a quantity called Hankel singular values — a measure of how much each internal state contributes to overall behavior — the team found they could reliably rank which dimensions matter after only about 10 percent of training. Once that ranking is set, the less-important pieces are discarded and the remaining 90 percent of training runs at the speed of a much smaller model.


"What's exciting about this work is that it turns compression from an afterthought into part of the learning process itself," said senior author Daniela Rus, an MIT professor and director of CSAIL. "Instead of training a large model and then figuring out how to make it smaller, CompreSSM lets the model discover its own efficient structure as it learns. That's a fundamentally different way to think about building AI systems."


The numbers are what make the case. On image-classification benchmarks, compressed models held nearly the same accuracy as their full-sized counterparts while training up to 1.5 times faster, per MIT News. A model shrunk to roughly a quarter of its original state dimension hit 85.7 percent accuracy on CIFAR-10 — versus just 81.8 percent for a model trained at that smaller size from scratch. On Mamba, one of the most widely used state-space architectures, the method delivered about 4x training speedups, compressing a 128-dimensional model down to around 12 dimensions while staying competitive. "You get the performance of the larger model, because you capture most of the complex dynamics during the warm-up phase, then only keep the most-useful states," Chahine said.


The distinction from existing tricks is theoretical grounding. Conventional pruning trains the full model and strips parameters afterward — so you still pay the full cost of training the big one. Knowledge distillation trains a large "teacher" to completion and then a smaller "student" on top, roughly doubling the effort. CompreSSM makes its cuts mid-stream, and in head-to-head tests against a recent spectral technique (Hankel nuclear norm regularization) it ran more than 40 times faster while achieving higher accuracy. The collaboration spans MIT CSAIL, the Max Planck Institute for Intelligent Systems, ELLIS, ETH, and Liquid AI.


There's a broader shift buried in the method. As the industry's default answer to better AI has been "make it bigger, then deal with the cost," CompreSSM points the other way — letting a model find its own lean shape while it learns. If that holds up beyond state-space models, the cheapest place to save compute may turn out to be the training run itself, not the cleanup afterward.


Written for Red Robot with AI assistance and human editing. Based on reporting by MIT News.

https://redrobot.online/2026/08/07/rr-16030-new-technique-makes-ai-models-leaner-and-faster-while-they-r/